Operating Line of Credit for Business: Costs, Uses and Repayment
Understand how an operating line of credit works for businesses, compare costs and learn when short-term funding may be appropriate.
Small business loans made simpler
Already exploring funding for a U.S. business? Start with the amount you actually need, the repayment your cash flow can support, and the total cost of each offer. Choose the guide that matches your financing decision:
Before accepting any offer: verify the lender, total borrowing cost, repayment frequency, guarantees and whether the payments remain affordable if revenue is delayed. Kevanzo provides educational information, not loan approvals or financing offers.
Understand how an operating line of credit works for businesses, compare costs and learn when short-term funding may be appropriate.
Understand business line of credit pre approval, credit checks, conditional offers and the information to verify before applying.
Compare a small business line of credit by lender requirements, borrowing fees, repayment terms and cash flow risk before applying.
A business term loan provides a defined amount of business capital that is repaid over an agreed period according to a repayment schedule. It can be useful when a business knows how much money it needs, what the money will fund, and which cash flow is expected to repay the debt. For broader comparisons, see … Read more
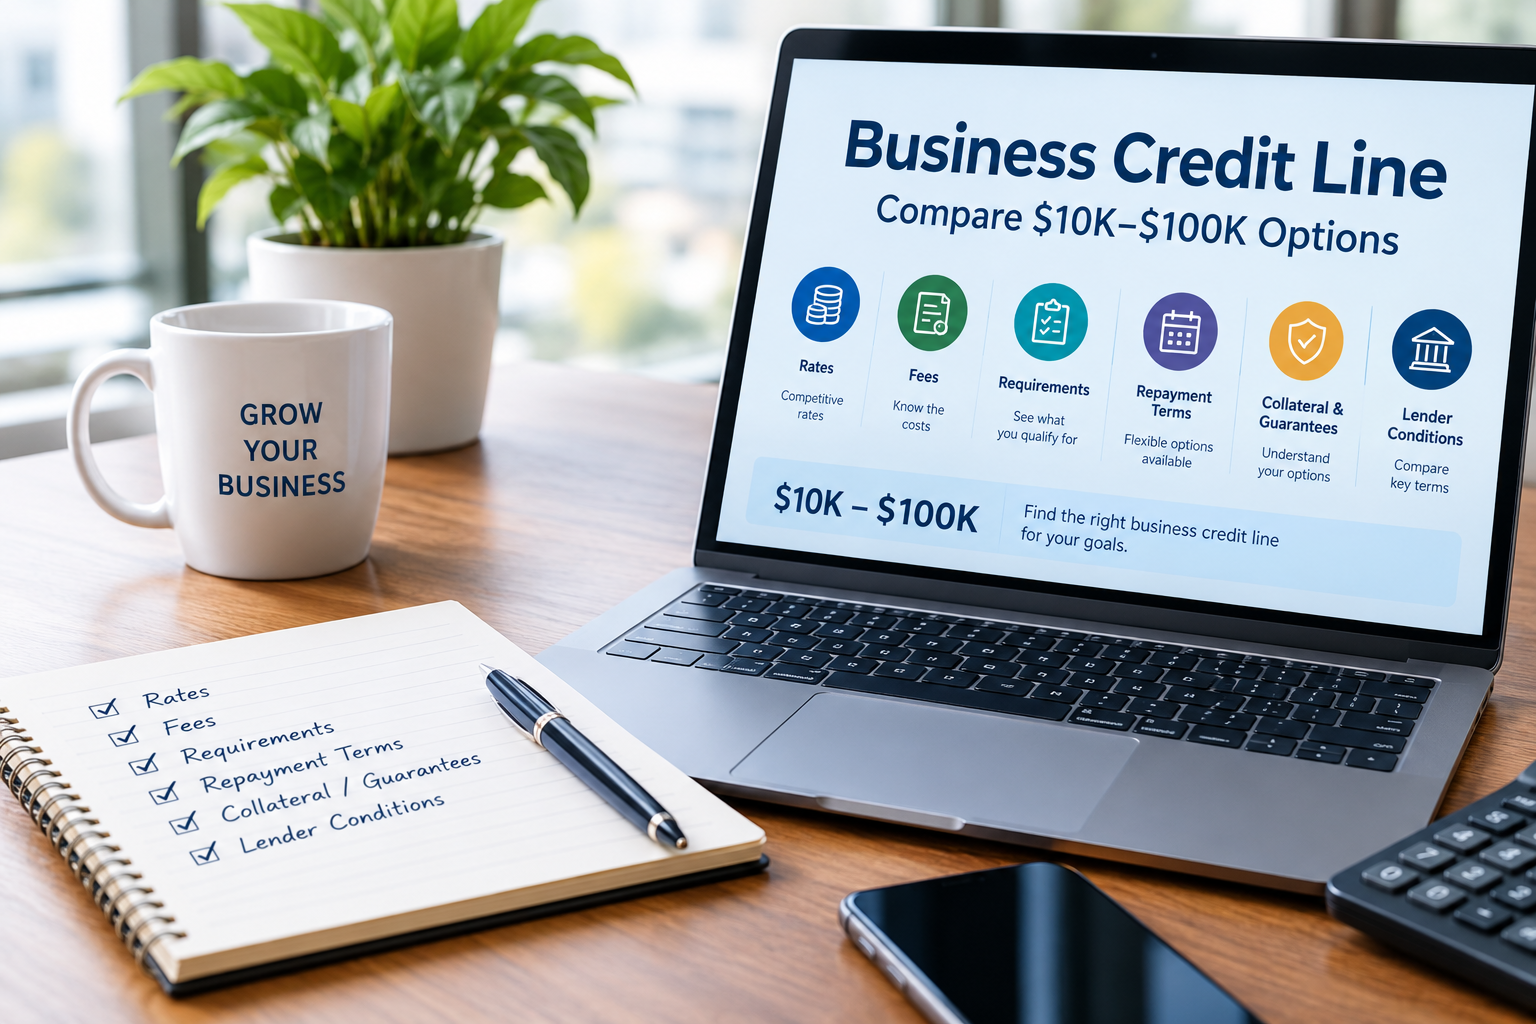
A business credit line gives a company flexible access to an approved amount of financing that can be drawn when needed rather than requiring the entire amount to be borrowed upfront. For businesses comparing roughly $10,000 to $100,000 in available credit, the real decision goes far beyond the advertised credit limit. A strong business credit … Read more
Business loans can provide capital for equipment, expansion, inventory, working capital, commercial property, acquisitions, refinancing, and other legitimate business needs. But finding available financing is only the beginning. A strong borrowing decision requires the business to identify the right financing structure, determine what it can realistically qualify for, compare lenders on the same basis, understand … Read more
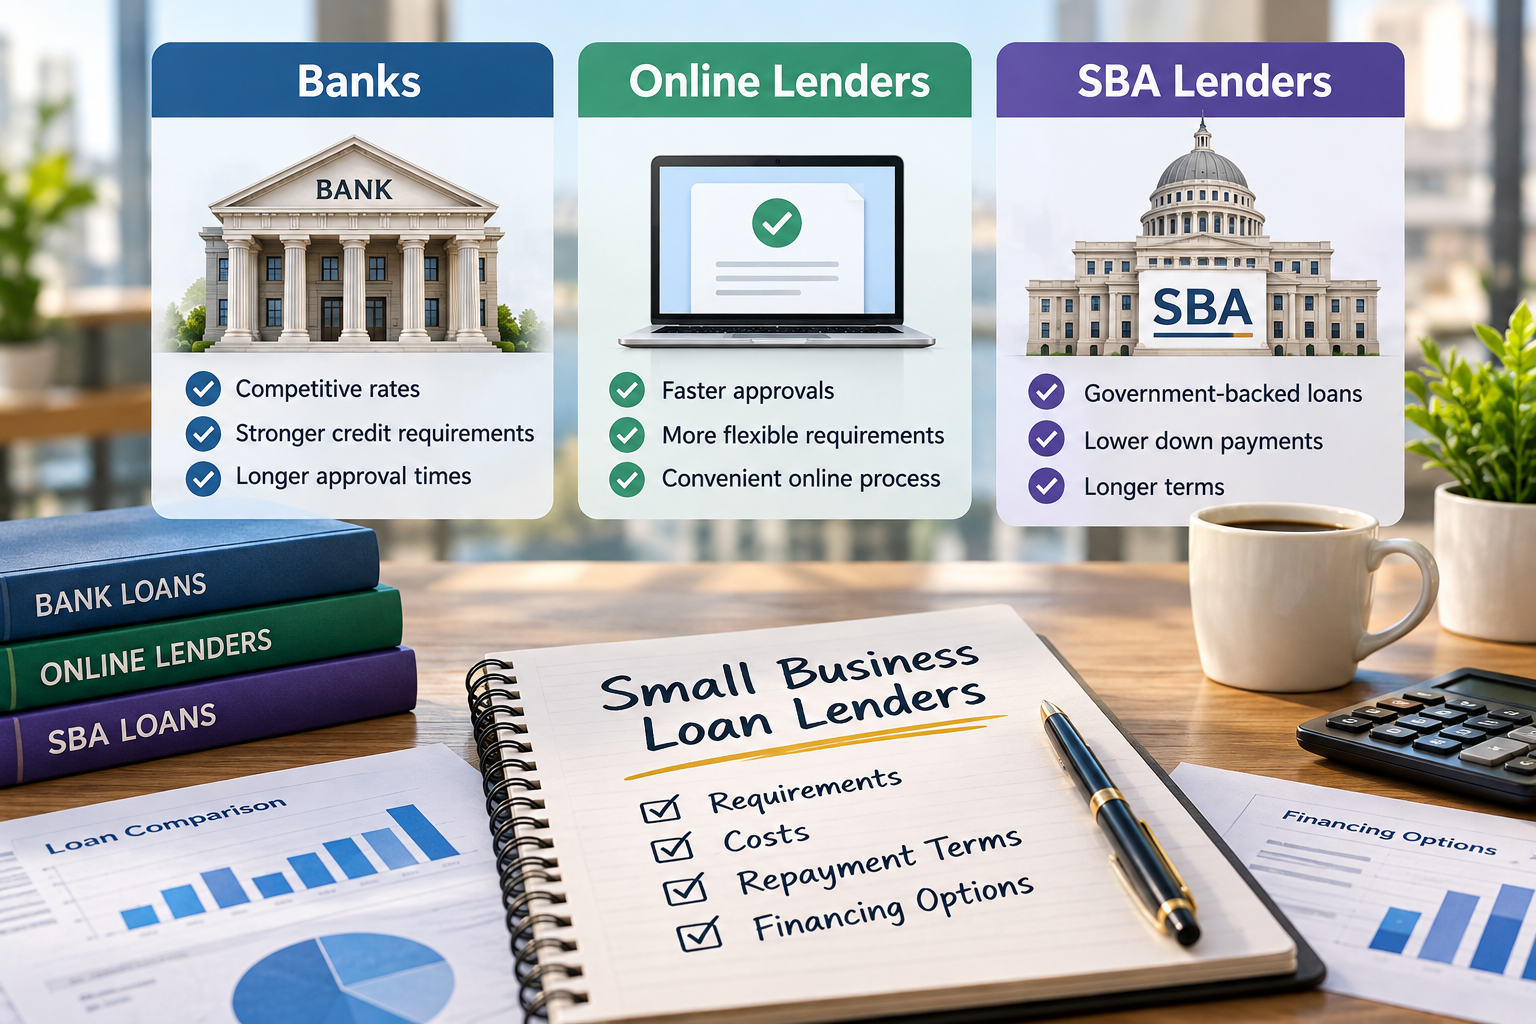
Small business loan lenders can differ just as much as the loans they provide. A bank may offer lower-cost financing but require stronger credit and a longer operating history. An online lender may make the application process faster but use shorter repayment periods or higher borrowing costs. An SBA-participating lender may offer government-backed financing, while … Read more
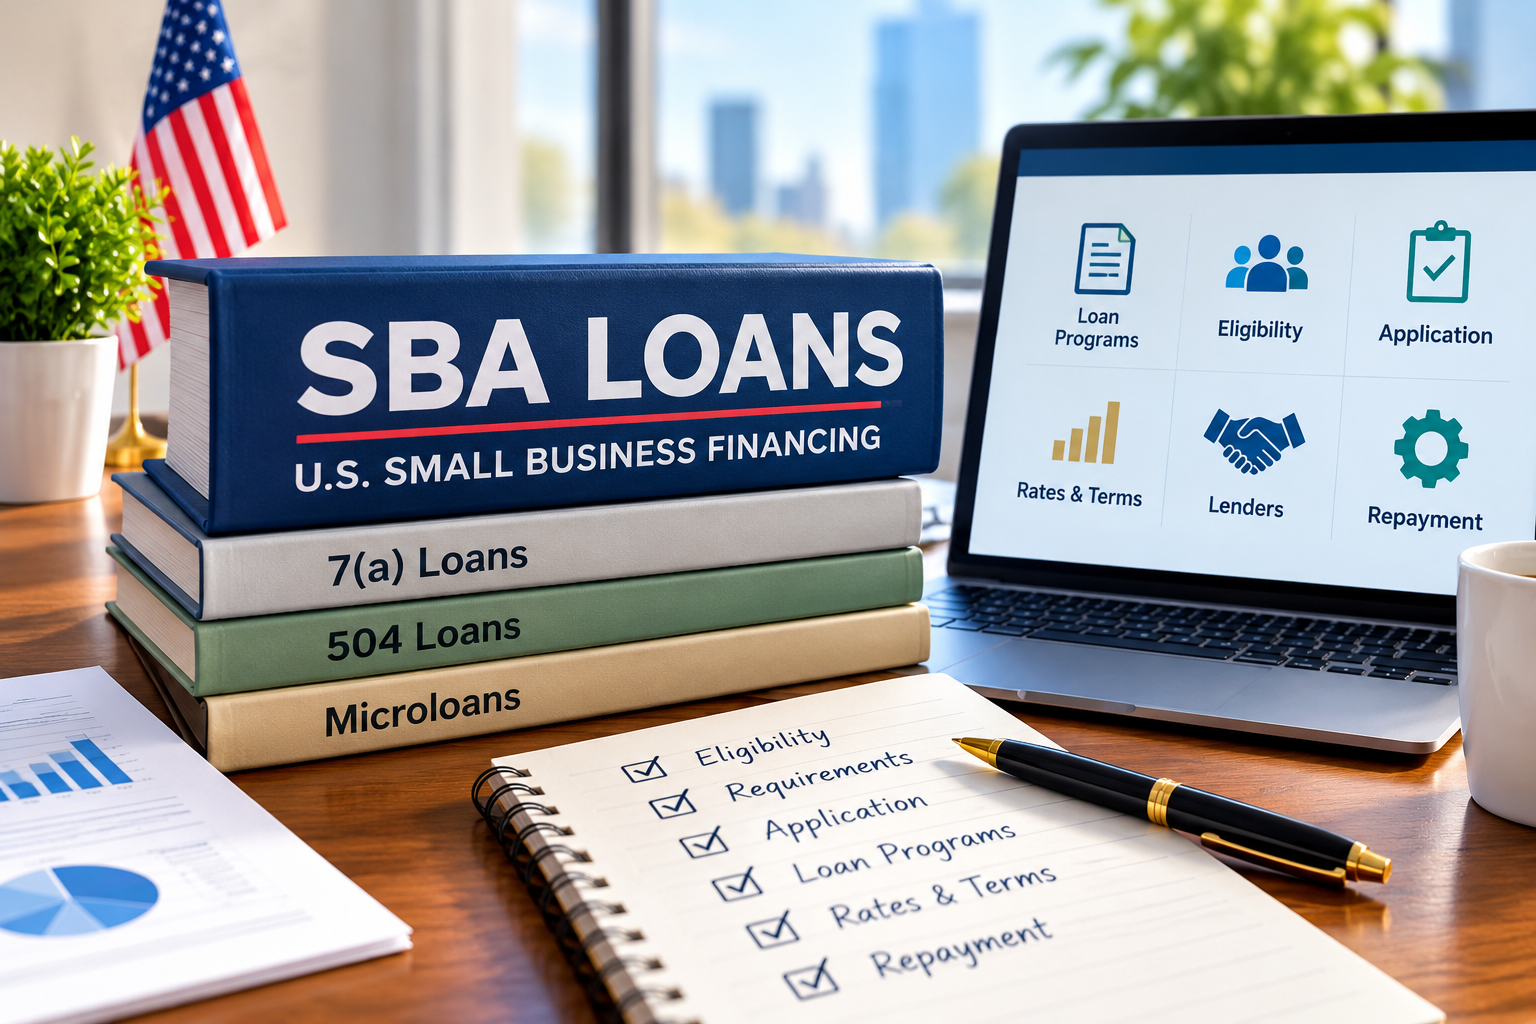
SBA loans are business loans made through participating lenders or approved intermediaries under programs supported by the U.S. Small Business Administration. They can help eligible U.S. small businesses finance working capital, equipment, real estate, business acquisitions, expansion and other permitted needs, but they are not automatic approvals and the SBA does not usually hand the … Read more
Startup business loans can help a new company pay for equipment, inventory, software, licensing, professional services, premises, marketing, working capital, and other legitimate launch or early-growth costs. The challenge is that a startup often has less operating history, fewer financial statements, and less proven cash flow than an established business. That difference changes both the … Read more
Startup Business Loans With No Revenue can sound contradictory. A new company may need money before it has customers, yet lenders usually want evidence that debt can be repaid. That tension is exactly why pre-revenue financing requires a different kind of analysis from financing an established company. A startup with no operating sales does not … Read more